


Delivering 4,000 MW of rooftop solar
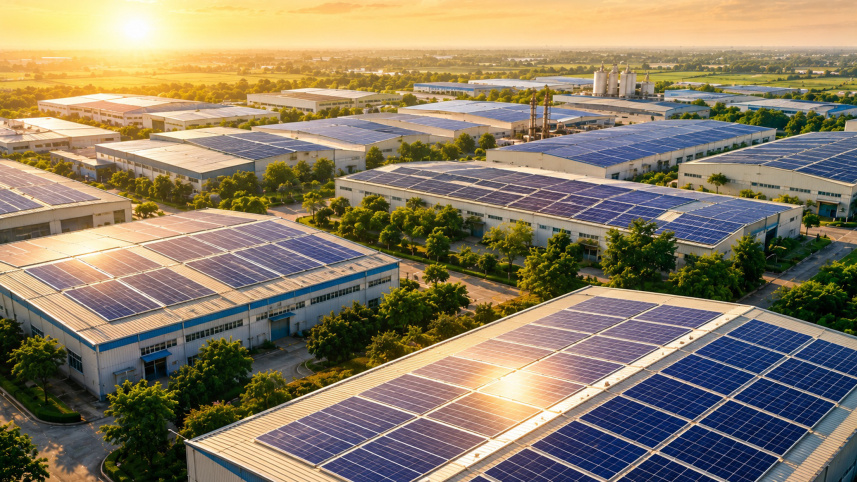
Bangladesh aims to add up to 4,000 MW of rooftop solar within one year. The newly announced incentive package, including a time bound Tk 10.50 per unit tariff for eligible surplus rooftop generation, together with the proposed OPEX model and battery storage framework, represents an important further step towards creating that market. The country has a large base of factories, textile and garment facilities, warehouses, commercial buildings, educational institutions, hospitals and public facilities with usable rooftop space. Achieving the target would require an estimated 24 million square meters of usable rooftop space nationwide. Daytime solar generation also aligns well with industrial and commercial electricity demand. Commercial and industrial (C&I) rooftop solar could therefore provide the fastest route towards realising the Government's ambition.
The challenge is converting these incentives and available rooftops into financed, connected and commissioned projects.
India added around 7,100 MW of rooftop solar in 2025 alone, taking cumulative capacity to approximately 23,500 MW by March 2026. Rapid large-scale deployment requires an integrated market architecture covering financing, contracts, utilities, grid connection, developers and execution.
The proposed shift towards third-party financed OPEX models, particularly Renewable Energy Service Company (RESCO) structures, is therefore important. Instead of investing their own capital, factory owners can contract a RESCO to design, finance, build, own and operate the solar plant, while purchasing electricity under a long-term agreement. But delivering 4,000 MW will require more than $2Bn dollars of capital and a much broader enabling framework. Five critical areas need to be addressed.
First, make projects financeable.
Mobilising capital at this scale will require a financing framework capable of attracting domestic and international financial institutions, development finance and foreign investment. Credit enhancement or partial-risk guarantees could help reduce financing costs and enable lenders to finance portfolios of rooftop projects.
The new tariff incentive can improve project economics, but it cannot substitute for access to long-term, competitively priced financing. For C&I projects in particular, the underlying economics will largely depend on electricity consumed directly by factories and businesses, with surplus exports providing an additional revenue stream.
Financing must also be supported by payment security and bankable contracts. If an investor installs a plant under a 15-year agreement, what happens if the factory closes, ownership changes or the electricity purchaser defaults? Standardised rooftop leases, RESCO power purchase agreements, termination provisions, lender step-in rights and payment-security arrangements are therefore essential.
Second, turn distribution utilities into facilitators.
Distribution utilities control critical elements of rooftop deployment, including technical approvals, connections, metering and electricity settlement. The new incentive package makes their role even more important as they will also administer the measurement and settlement of surplus electricity.
Each utility should receive annual and monthly MW targets, supported by measurable service standards for technical approvals, meter installation and commissioning.
Utility-Led Aggregation (ULA) should also be considered. Rather than waiting for customers to originate projects individually, utilities can identify and aggregate suitable rooftops and competitively procure RESCOs to finance and develop them as portfolios. A utility could, for example, aggregate 50–100 MW of commercial, residential or public-sector rooftops into a programme, reducing transaction costs and improving financing. ULA should complement and not replace privately originated RESCO projects.
This creates three parallel engines for deployment: private C&I/RESCO investment, utility-led aggregation and aggregated solarisation of Government buildings.
Third, enable scale and competition.
Local service capability is important, but strong geographic preferences risk fragmenting the market into district-level territories. Large-scale delivery will require experienced developers, strong EPC companies, portfolio financing and economies of scale. National accreditation combined with regional service requirements would be more effective.
Providers should also be classified by capability. The technical and financial requirements for installing a 5 kW household system cannot be the same as those for financing and operating a multi-megawatt industrial portfolio. Separate accreditation categories should therefore cover residential installers, commercial EPC contractors, industrial developers and large RESCO investors.
Fourth, make grid access predictable.
Net-metering and interconnection rules should increasingly be determined by technical grid capacity rather than historical electricity consumption. If a factory has sufficient rooftop space and the local network can safely accommodate the generation, there should be a pathway to install the economically optimal capacity.
The new Tk 10.50 grid-feed tariff should help accelerate deployment, particularly for projects commissioned within the incentive window. However, the February 2027 deadline may be too short to drive meaningful scale, given the time required for project development, financing, approvals, procurement and commissioning. A time-bound incentive should ultimately transition into a transparent long-term pricing methodology that provides investors with durable certainty. Bankability depends not simply on the attractiveness of today's tariff, but on confidence in the rules governing an asset over its operating life.
The inclusion of battery energy storage (BESS) is also welcome. As rooftop penetration increases, storage can play an increasingly important role in grid integration and maximising the value of distributed generation.
 For all latest news, follow The Daily Star's Google News channel.
Fifth, create one national execution mechanism.
A National Rooftop Solar Mission, supported by a dedicated Programme Management Unit with clear authority and accountability, should coordinate distribution utilities, financial institutions, developers and relevant Government agencies. A single digital platform should cover registration, financing, vendor selection, technical approval, installation, metering, commissioning, settlement and performance monitoring.
The headline target must then be converted into an execution pipeline. Delivering the required commissioned capacity may require a 5,000–6,000 MW development pipeline to account for projects that are delayed, fail to reach financial close or ultimately do not proceed. Monthly milestones should track project identification, approvals, financing, construction and commissioning, with progress transparently reported.
Bangladesh has the rooftop potential and now has an important new incentive framework. But delivering at scale will require substantial private capital. Government's critical role is to establish a clear and predictable policy framework and a bankable investment environment capable of attracting domestic and international financial institutions and foreign investment. The priority now is ensuring that it translates into financed, connected and commissioned megawatts.
The author is a strategic consultant across technology, media and infrastructure industries.
Comments