


Q-Cash outage: A wake-up call for Bangladesh's banks
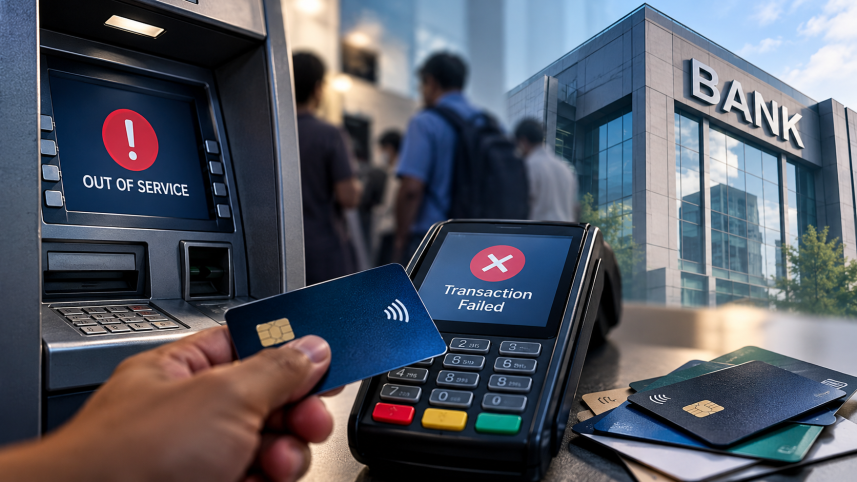
The recent severe disruption in card-related transactions across 30 to 33 commercial banks in Bangladesh—triggered by a migration attempt by IT Consultants Limited (ITCL)—has provided a striking case study for the nation's financial and capital markets. ITCL was attempting to transition its core card management infrastructure from Compass Plus to OpenWay.
However, migration friction, back-end disputes and a lack of vendor support triggered a catastrophic system collapse. The resulting paralysis forced central bank intervention and strict regulatory scrutiny, compelling a rollback to the older platform. Crucially, this is not an argument to dismantle fintech ecosystems, but a cautionary case study on the perils of absolute dependency on external infrastructure.
A multi-layered financial crisis
The timing of the shutdown coincided with peak monthly salary disbursements, affecting many low-income workers. Across 30 to 33 Q-Cash member banks, an estimated 1.5 million-plus cards became inactive. According to Bangladesh Bank's 2025 data, there were 8.23 million debit and 792,000 credit cardholders, highlighting the massive scale of the disruption.
The ATM dependency trap
ITCL operates over 2,200 ATMs within the Q-Cash network, compared with Bangladesh Bank's 12,713 national ATMs in 2025. Because numerous commercial banks rely on these shared ATMs rather than deploying their own, the blackout trapped clients from various other institutions.
Broader disruptions
The instant transfer channels under the National Payment Switch Bangladesh (NPSB) were offline, affecting a platform whose transactions grew 98 percent in volume and 103 percent in value year-on-year in 2025. Credit card holders incurred penalties, and Bangla QR, which had 963,000 merchants with a transaction value of Tk 27 billion, faced intermittent disruptions.
The ripple effect
A dimension often overlooked in corporate tech failures is the collateral damage inflicted on capital market investors. On October 4, 2026, ITCL's shares closed at Tk 42.90. On October 5, the price fell to Tk 41.60—a 3.03 percent decline—with volume surging to 524,684 shares. By October 6, the stock closed at Tk 41.40, down 0.48 percent, with a market capitalisation of around Tk 5.32 billion and an 11.44x price-to-earnings ratio, eroding retail and institutional portfolio values. The company's September 30, 2026 shareholding pattern (sponsors 51.09 percent, institutions 14.15 percent, foreign 0.20 percent, public 34.56 percent) meant the outage impacted a broad base of shareholders.
Erosion of trust
Amid high nonperforming loans and more than 81,000 fraud cases, as noted in Bangladesh Bank's 2025 report, this sweeping outage further eroded customer trust and pushed corporate clients to re-evaluate their banking partners. Amid this crisis, proactive measures were taken by the central bank and commercial bank authorities.
Top management jumped into crisis-management mode, executing manual cash dispatches to factories and coordinating service restoration. Concurrently, Bangladesh Bank stepped in swiftly under the Payment and Settlement Systems Act, 2024, summoning ITCL's management and initiating strict oversight, which proved crucial in forcing the legacy rollback.
Debunking the "high cost" myth
Bank managements often shy away from proprietary switching systems, citing high initial CapEx. However, through long-term amortisation over a 10-to-15-year lifecycle, annual costs become manageable. Furthermore, third-party fees scale linearly with transaction volumes, whereas proprietary switches scale efficiently, lowering marginal costs over time. Bangladesh Bank's 2025 data shows total payment transactions grew 19% to 10.8 billion, making investing in proprietary or multi-vendor switching systems a strategic necessity.
A pragmatic roadmap: phased implementation
Banks do not need to overhaul everything overnight; a phased approach mitigates risks:
Phase 1: Implement an independent switching system integrated exclusively with debit cards. This ensures internal card transactions and NPSB-enabled IBFT channels remain operational. Covering 8.23 million debit cardholders, this provides maximum resilience.
Phase 2: Gradually onboard credit cards (792,000 holders) and prepaid cards once core infrastructure stabilises.
Phase 3: Integrate with multiple switching networks, including Bangladesh Bank's TakaPay national card scheme (adopted by 17 banks), to eliminate single points of failure.
The ITCL-OpenWay migration fiasco should be viewed strictly as a strategic wake-up call, not an indictment of third-party vendors. Fintech partnerships are essential, but banks must retain strategic control over their core switching capabilities. By treating IT infrastructure investment as an essential shield for business continuity, customer protection and shareholder value rather than as an overhead cost, Bangladesh's financial sector can prevent future digital blackouts and safeguard public trust.
The decisive coordination between bank senior managements and the central bank under the Payment and Settlement Systems Act, 2024, successfully averted a prolonged disaster. Prevention remains far better than cure, and the Q-Cash case study should become mandatory reading for every bank board, risk committee and technology leadership team in Bangladesh—and beyond.
The writer is a vice president and head of card at Midland Bank PLC.
 For all latest news, follow The Daily Star's Google News channel.
Comments