


Women-led MSMEs lead in digital finance, still face heavy loan barriers: study
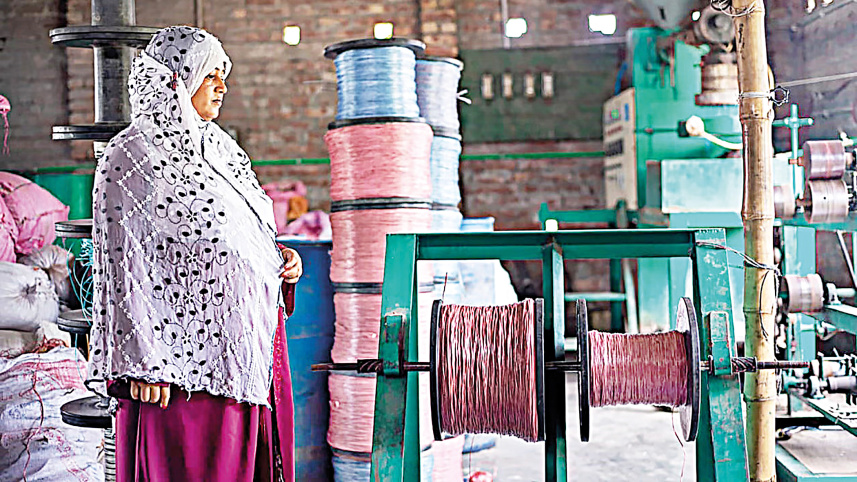
Women-led micro, small, and medium enterprises (MSMEs) in Bangladesh exhibit higher digital footprints and stronger interest in digital credit than male-led businesses, yet they continue to face significant barriers to formal financing, according to a study.
The study, titled “Ecosystem Mapping and Diagnostic Study on MSME Financing,” conducted by LightCastle Partners under The Asia Foundation’s “Bridging the Gap” project, examined financing bottlenecks across administrative divisions.
The research surveyed 329 MSMEs across all eight administrative divisions alongside key informant interviews with bankers, fintech operators, and industry experts.
Overall, the study found that 95.2 percent of MSMEs face liquidity shortages, with the nationwide financing gap estimated at $2.8 billion.
Against this broader financing gap, women-led enterprises show distinct digital adoption patterns. The survey found that women entrepreneurs use an average of 2.75 digital platforms—including mobile financial services (MFS), social commerce, and digital payment channels—compared to 1.88 platforms for male-led enterprises.
Additionally, 83 percent of women-led MSMEs expressed interest in accessing digital credit solutions to expand operations and cover working capital needs, compared to an overall 74 percent demand across all surveyed MSMEs.
Despite higher digital readiness, actual loan disbursement to female entrepreneurs remains disproportionately low, with women-led businesses receiving under 10 percent of total formal SME credit distributed by commercial banks and financial institutions.
Researchers highlighted that formal lenders continue to rely heavily on traditional fixed-asset collateral and extensive paper documentation, which women entrepreneurs frequently lack due to systemic asset-ownership disparities.
The report noted that while digital platforms capture substantial transactional and behavioural data from women-led enterprises, financial institutions have yet to integrate alternative credit-scoring models that utilise these digital footprints.
Consequently, high digital activity fails to translate into accessible credit lines.
"Women-led enterprises demonstrate strong digital adoption and reliable repayment potential, but traditional underwriting frameworks fail to capture these digital signals," the study said.
To bridge this gap, the report recommended funding targeted, agent-led onboarding pilots prioritising women-owned firms, establishing consented data-sharing frameworks, and incentivising banks to adopt alternative credit-scoring tools based on transaction histories rather than physical collateral.
 For all latest news, follow The Daily Star's Google News channel.
Comments